How the ATO Knows So Much About You and Why Transparency Protects You
How the ATO Knows So Much About You and Why Transparency Protects You
Your tax return is only one source of information available to the Australian Taxation Office. Banks, employers, super funds and other organisations also provide data that the ATO can compare with what you report. Understanding how this works can help you avoid missed income, incorrect claims and unnecessary questions at tax time.
The short answer: the ATO uses data matching to identify possible differences between your tax records and information supplied by others. Its information is extensive, but it does not provide a complete picture of your finances and may contain errors. You still need to check your return and tell your tax agent about anything missing.
For employees, investors and business owners, the practical message is straightforward: keep reliable records, report what is required and raise anything you are unsure about before lodging. Hoping an omission will go unnoticed can turn a manageable issue into a more expensive problem.
1. Where Does the ATO Get Its Information?
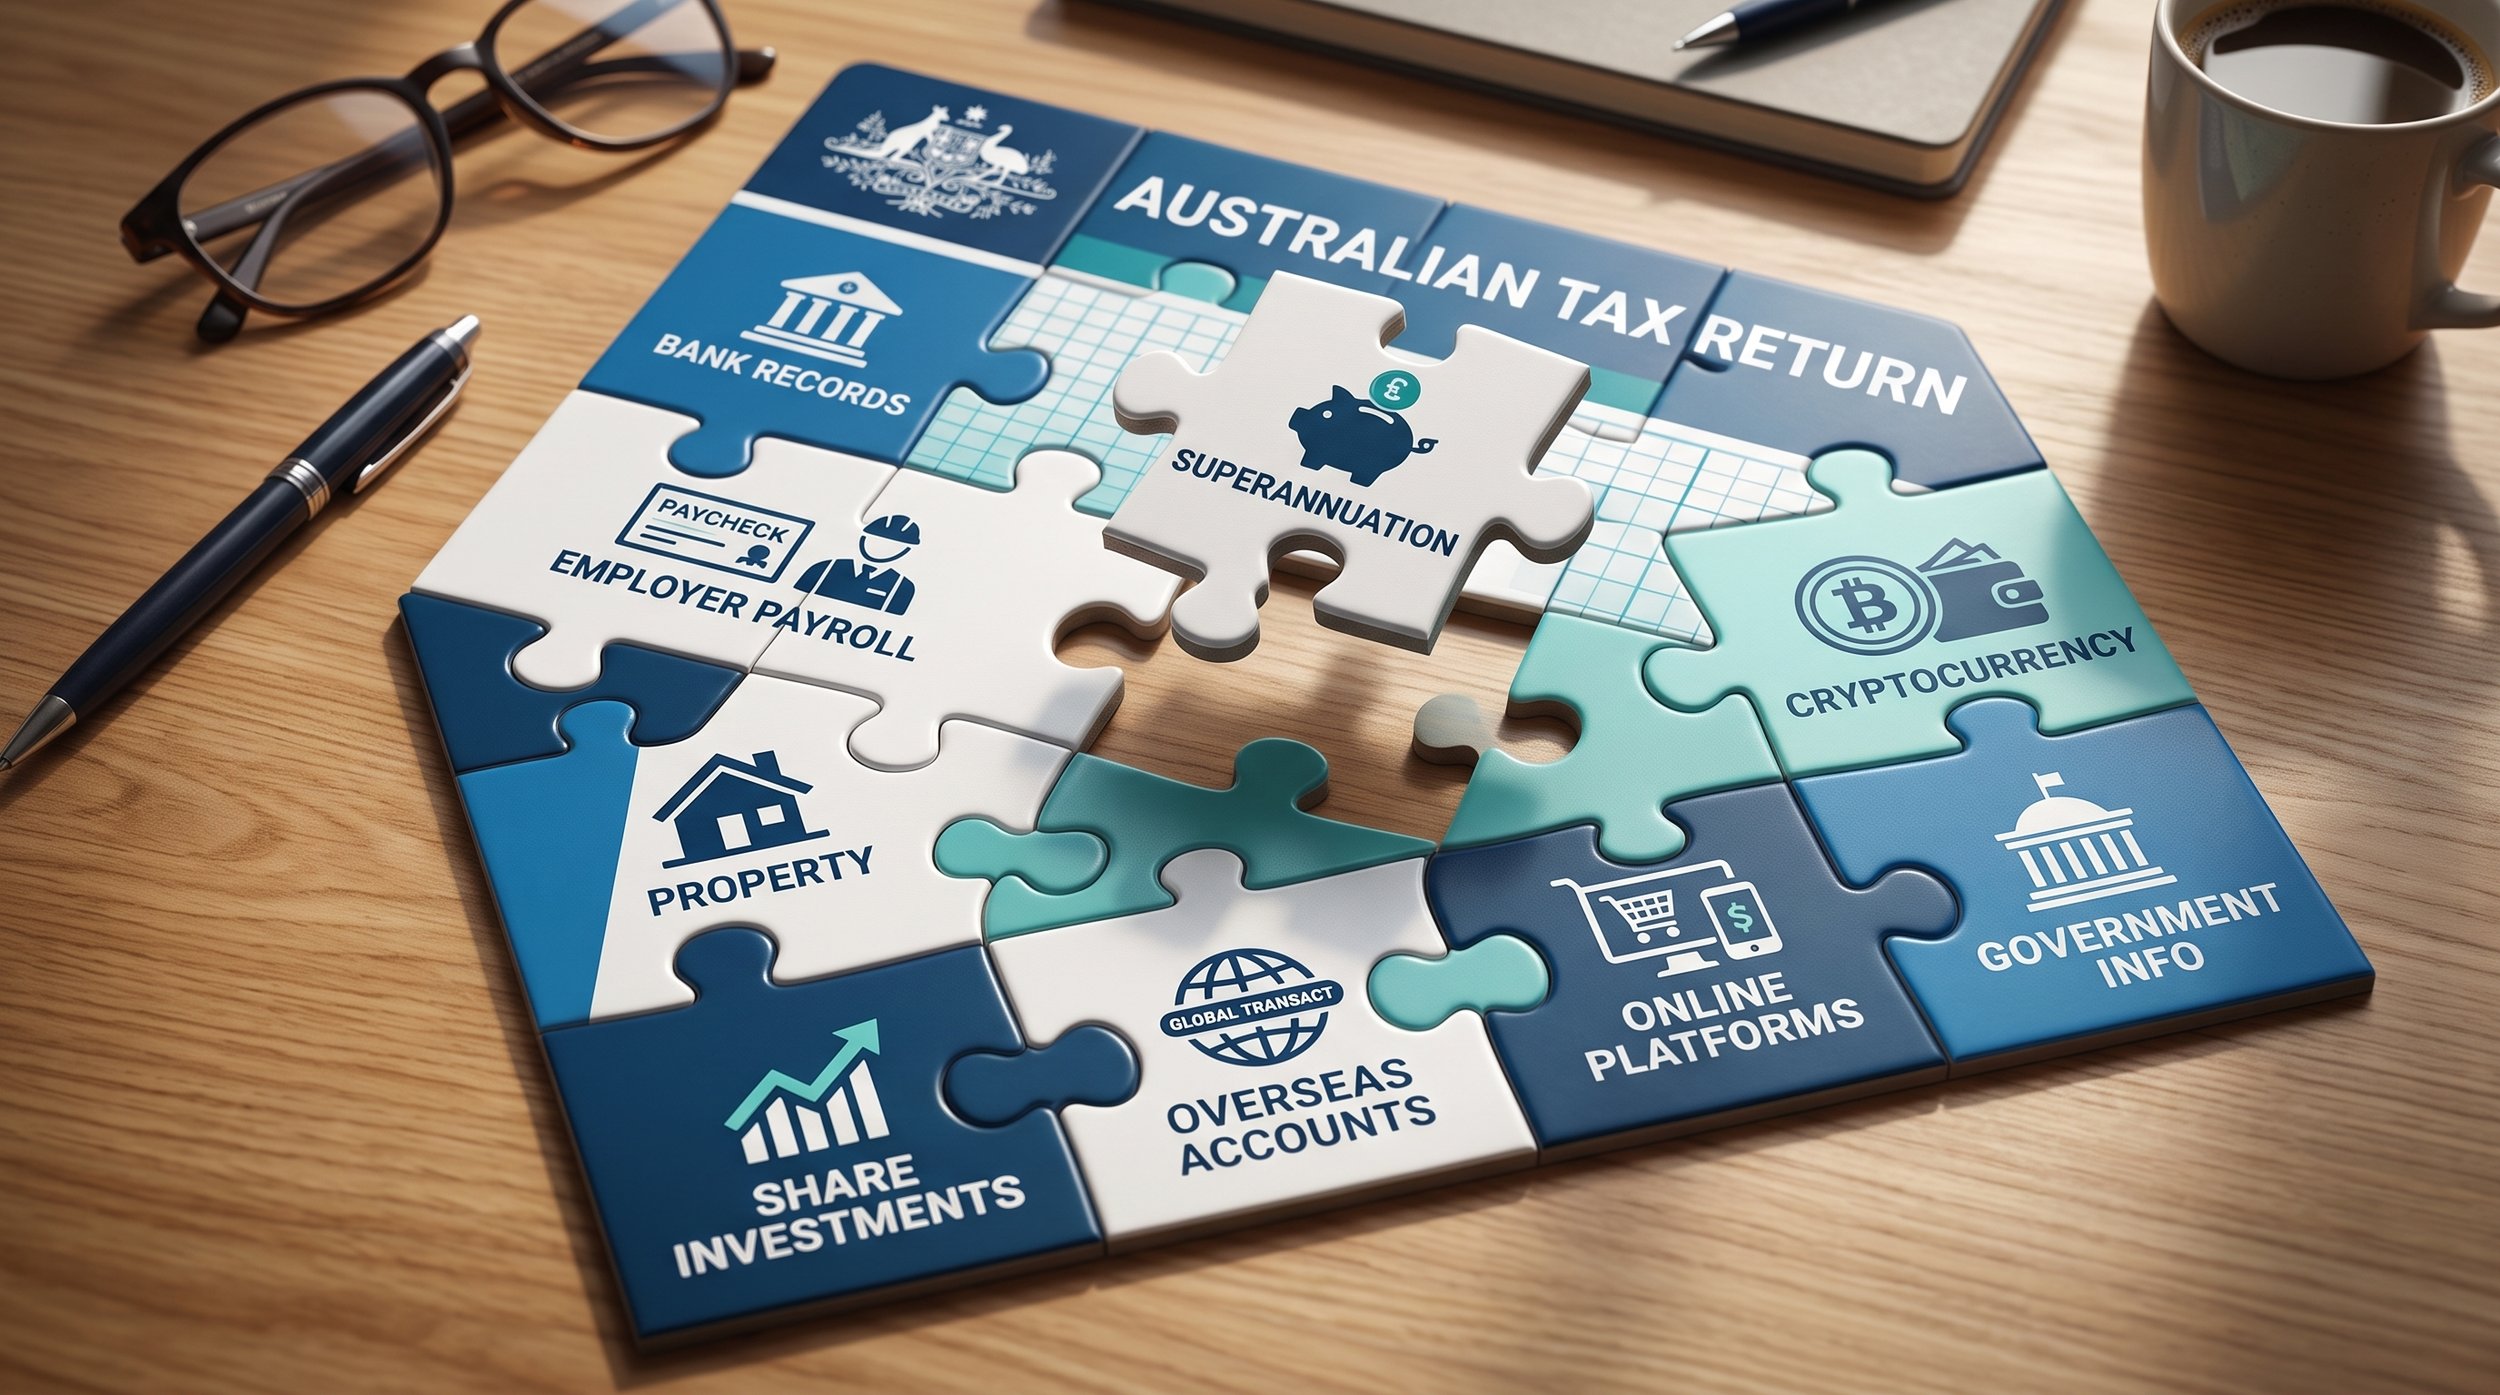
Some organisations have a legal obligation to report information to the ATO. The ATO also obtains information through specific data matching programs and exchanges with overseas tax authorities.
Banks provide reportable information such as interest income. Employers report salary, wages, tax withheld and super liability information through Single Touch Payroll. Super funds also report contributions, account information and certain benefits.
The picture extends beyond employment and banking. Property records, investment transactions, crypto activity and information from some online platforms can help the ATO identify activities that may need to appear in a return. Selected insurance information and records from other government agencies can also be used under relevant programs.
International arrangements allow the exchange of reportable overseas financial account information and other tax information. This can be relevant for Australians with foreign income or investments, as well as people whose tax residency has changed.
📖 What do these words mean?
Data matching: Comparing information from different sources to identify possible inconsistencies. For example, a bank may report interest that does not appear in the customer's tax return.
STP (Single Touch Payroll): The system employers use to report payroll information, including wages, tax withheld and super liabilities, generally each payday.
PAYG withholding: Tax an employer or other payer withholds from certain payments and sends to the ATO.
This does not mean every transaction, asset or overseas property is automatically reported. It does mean that leaving something off a return does not necessarily leave it outside the ATO's view.
2. Why Information Pre-Filled by the ATO Still Needs Checking
The ATO uses information from other organisations to pre-fill parts of tax returns and help identify reporting errors. This can make tax time easier, but information pre-filled by the ATO is a starting point rather than a complete checklist.
Information may arrive late, contain errors or need further interpretation. A share transaction record, for example, may indicate a sale without providing everything needed to calculate the correct capital gain or loss.
Imagine you sell shares that you bought several years ago. The sale proceeds alone do not establish your taxable gain. Purchase costs, brokerage and relevant adjustments may also need to be considered. Your tax agent needs those records to work out the correct result.
You may also have income that does not appear automatically, such as cash payments, some overseas earnings or income from a side business. An amount being absent from the information provided by the ATO does not determine whether it is taxable.
Good to know: The aim is to prepare a correct return, rather than simply copy the ATO's figures. If information supplied by another organisation is wrong, it should be checked and addressed.
What to do now: Compare the information in your return with your own records. Tell your tax agent about all relevant income and transactions, including items that do not appear in the information pre-filled by the ATO.
3. What Happens if Your Tax Return Does Not Match?
A discrepancy can lead to questions, a review or an amended assessment. The ATO may identify differences when you lodge or after your assessment has been issued.
However, a mismatch does not automatically mean you have deliberately done something wrong. There may be a reporting error, a timing difference or an amount entered under a different label. The ATO explains that taxpayers may be given an opportunity to check their records and confirm the correct amount.
Where income has been omitted or a deduction overstated, you may need to pay additional tax and interest. Penalties can also apply, depending on the circumstances and whether reasonable care was taken. Deliberate concealment can have more serious consequences, including prosecution in serious cases.
Good to know: An honest mistake is not automatically treated as deliberate concealment. The reason for an error and the care taken matter when penalties are considered. A voluntary disclosure may reduce penalties in eligible circumstances, depending on its timing and the relevant rules.
If you receive a notice, start by finding out exactly which amount or transaction is being questioned. Your records may explain the difference, or they may show that a correction is needed. Responding with clear evidence is more useful than guessing why the figures differ.
What to do now: Check the response deadline on any ATO notice and send it to your tax agent. If you discover an error yourself, seek advice about correcting it promptly rather than waiting for the ATO to contact you.
4. Accurate Records Matter More Than Guesswork

Tax rules can be confusing, particularly when your circumstances change. Starting a side hustle, selling investments, renting out a room or moving overseas can introduce obligations that did not apply before.
You are responsible for reporting assessable income, making supported claims and providing information required by the return. This does not mean every person must declare every asset they own. The information required depends on the tax rules and your circumstances.
Keep records of income, expenses and relevant transactions, including purchase information needed when an asset is eventually sold. For deductions, retain evidence of what you paid and how the expense relates to earning income.
A receipt proves a purchase occurred, but it does not necessarily prove that the purchase is deductible. For an item used both privately and for work, you may also need records showing how you calculated the portion used for work.
What to do now: Organise your records throughout the year and raise unfamiliar transactions before lodging. If your work, property use or overseas circumstances change, ask what records you should start keeping.
5. How Your Tax Agent Can Help
Your tax agent can compare ATO information with the records you supply, identify gaps and apply the tax rules to your circumstances. That work depends on having the full picture.
For example, knowing that you sold shares is useful. Having the purchase records, sale statement and details of relevant corporate actions is what helps your agent calculate the outcome correctly. The same principle applies to rental income, crypto transactions and overseas activities.
At JPR Business Group, we can help you:
- Review differences between your records and ATO information.
- Identify income and transactions that need reporting.
- Check deductions and the evidence supporting them.
- Correct previous returns where needed.
- Understand ATO correspondence and prepare a response.
- Plan for changes in your business, investments or overseas circumstances.
Professional advice can reduce the risk of avoidable mistakes, but no adviser can guarantee that a return will never be reviewed or that penalties will never apply. Sharing complete and accurate information gives your adviser the best basis to help.
What to do now: Before lodging, tell us about side income, investment sales, crypto activity, rental arrangements and relevant overseas interests. If you are unsure whether something matters, raise it so we can check.
Frequently Asked Questions
Does the ATO know about all my bank transactions?
The ATO receives reportable information from banks and can obtain other information through its lawful powers and data programs. That does not mean every transaction in every account automatically appears in your tax return.
Can I leave out income if the ATO has not pre-filled it?
No. Assessable income must be reported even if it is missing from the information pre-filled by the ATO. Check your records and tell your tax agent about anything additional.
Does an ATO mismatch mean I will be fined?
No. A mismatch needs to be investigated. The correct tax treatment, the reason for the discrepancy and the care taken all matter when determining whether a penalty applies.
What should I do if I have already lodged an incorrect return?
Speak with your tax agent promptly. They can check whether an amendment or voluntary disclosure is appropriate and explain any additional tax, interest or penalty implications.
Unsure What You Need to Report?
Whether you have extra income, investment transactions, overseas interests or an ATO letter you do not understand, speak with JPR Business Group. We can help you check the details and work out what to do next.
Contact JPR Business GroupFurther information: ATO guidance on data matching, ATO guidance on penalty remission. This article provides general information. Contact JPR Business Group for advice relevant to your circumstances.