Lost Super, Overseas Travel & Property Tax Changes: Your October 2026 Update
Lost Super, Overseas Travel & Property Tax Changes: Your October 2026 Update
Could an old super account be holding money you have forgotten about? Does spending time overseas change your Australian tax obligations? This October, we explain four practical tax and super updates that could affect your finances, your property investments and your retirement plans.
Our roundup covers the ATO's passenger movement checks, how to search for lost super, changes protecting certain property owners under the negative gearing reforms, and why SMSF trustees should regularly review their investment strategy.
1. Overseas Travel: The ATO Can Check Your Arrival and Departure Records
If you regularly travel overseas, have moved abroad or split your time between countries, your travel dates can matter when preparing your Australian tax return.
The update: The ATO's latest passenger movement data-matching program covers the 2026-27 to 2028-29 financial years. Travel information from the Department of Home Affairs can be compared with tax records to help identify potential residency, reporting and lodgement issues.
Why it matters: Australian tax residents are generally taxed on worldwide income, while foreign residents are generally taxed on Australian-sourced income. Your status can also affect the tax-free threshold, Medicare levy obligations and the tax treatment of an Australian property sale.
Leaving Australia does not automatically make you a foreign resident for tax purposes. The assessment considers your living arrangements, family connections, intentions and other circumstances. Citizenship and visa status do not settle the question either.
What does “tax residency” mean?
It is your status under Australian tax law, which determines how Australia taxes your income. It can differ from your immigration residency status.
For example, someone who takes an overseas work assignment but keeps strong family and living connections in Australia may still be an Australian tax resident. Someone relocating permanently may have a different outcome. The dates help explain the situation, but they are only part of the evidence.
What to do now: Keep a record of international arrival and departure dates, flight itineraries and supporting documents. Tell your accountant about extended overseas stays or a planned relocation before lodging your return or signing a contract to sell an Australian property.
2. More Than $21 Billion in Lost Super: Could Some of It Be Yours?
An old job, a change of address or a forgotten account could mean some of your retirement savings are sitting outside the super fund you currently use.
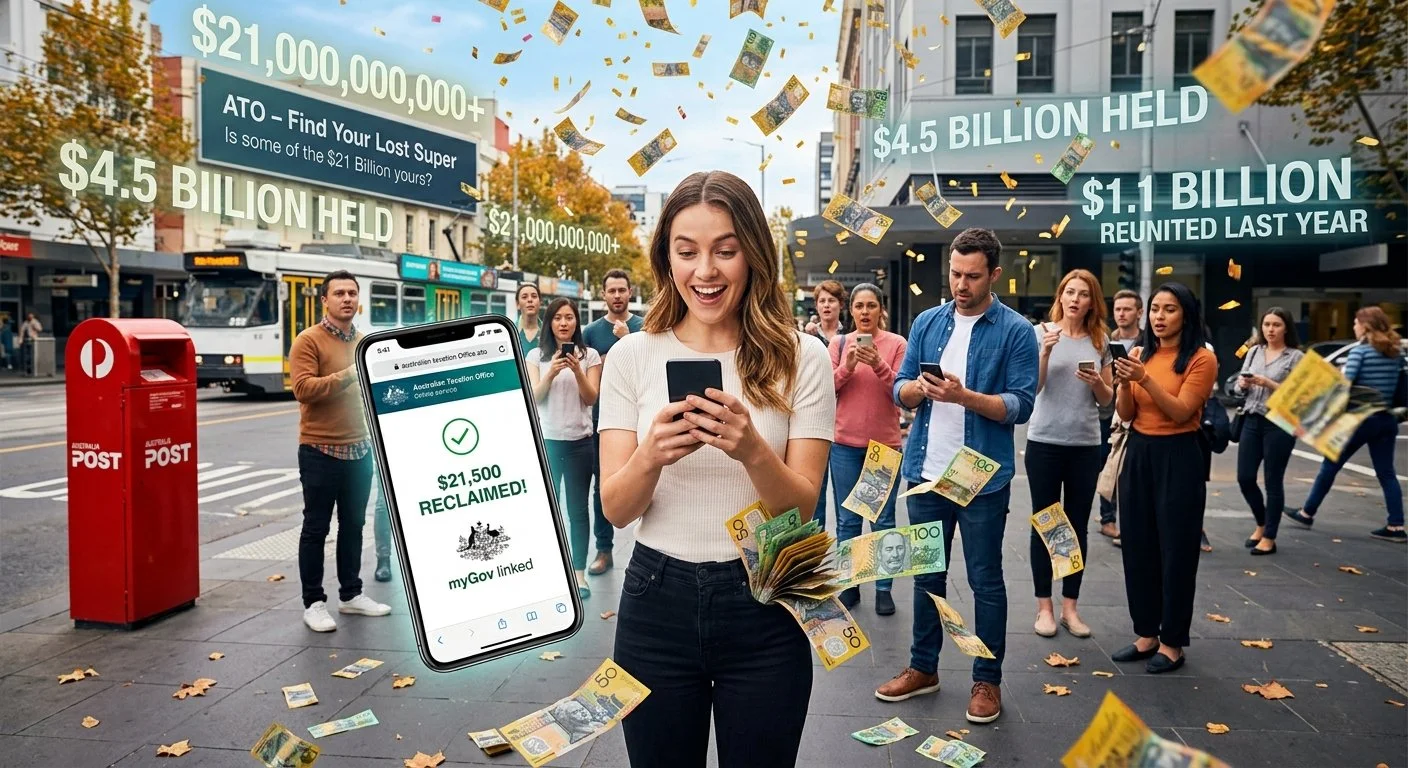
The update: More than $21 billion in lost and unclaimed super is waiting to be reunited with its owners. A free search can help you locate accounts you have lost track of.
Super can become lost when a fund cannot contact you or an account becomes inactive. In some circumstances, the money is transferred to the ATO for safekeeping until it is claimed.
How to check:
- Sign in to your myGov account and open your linked ATO service.
- Select the Super section and review your fund details.
- Check for old accounts, lost super and any ATO-held balances.
Finding another account may make a useful difference to your retirement savings, especially if retirement is approaching. You can find more information through the government's Moneysmart guide to finding lost super.
Before combining accounts, compare fees, investment options and insurance. Death, total and permanent disability or income protection cover may end when you close an account. Transferring money does not guarantee better returns, and replacing existing insurance may not be straightforward.
What to do now: Run the free search and update your contact details with your funds. If you find multiple accounts, check the insurance and other benefits before arranging a rollover.
3. Negative Gearing Fixes Protect Certain Transfers and Former Homes
The negative gearing reforms taking effect from 1 July 2027 have raised questions for people who already own residential property, particularly where ownership changes or a former home becomes a rental.
The background: Under the reforms, losses from affected established residential properties will generally be restricted to residential property income and gains, rather than being offset against wages or other unrelated income. Properties held before 7:30 pm AEST on 12 May 2026 generally retain their existing treatment.
What is negative gearing?
A property is negatively geared when its deductible costs exceed the income it earns. The tax rules determine whether that loss can reduce your other taxable income or must be carried forward.
The update: Changes address unintended outcomes where a protected property interest passes following a spouse's death or a relationship breakdown. Certain transfers involving an existing co-owner may also qualify for protection.
For example, a couple who bought an investment property in 2019 should not assume that a surviving spouse automatically loses the property's protected treatment when inheriting the other ownership share. The circumstances and transfer rules still need to be checked.
A related correction addresses eligible homes bought before the Budget announcement that are later rented out. A technical rule that can reset a property's acquisition value when it first produces income is disregarded when determining its acquisition date for negative gearing purposes.
This means a homeowner who bought before the cut-off and later moves out may retain the property's protected negative gearing treatment. However, the property's capital gains tax position requires a separate assessment. Protection under one set of rules does not automatically establish an exemption under another.
What to do now: Keep purchase contracts, ownership records and documents relating to any transfer. Seek advice before changing ownership or turning your home into a rental, so you understand both the negative gearing and CGT consequences.
4. SMSF Trustees: Does Your Investment Strategy Still Fit Your Retirement Plans?
An SMSF investment strategy should explain how the fund's investments support its members' retirement needs. It needs to remain appropriate as those needs change.
The requirement: Trustees must formulate, regularly review and follow an investment strategy that considers the fund's circumstances. The ATO expects reviews at least annually, and significant changes may call for an earlier review.
A member starting a pension, someone joining or leaving the fund, or a major market movement can all affect whether the existing strategy remains suitable.
Your review should consider:
- Investment risks and expected returns.
- The mix of assets and risks from a lack of diversification.
- Whether investments can provide cash when the fund needs it.
- The fund's ability to pay expenses, liabilities and member benefits.
- Whether insurance for members should be held within the fund.
For example, a fund holding mostly property may have suited members while they were contributing and building savings. Once pension payments begin, rent and available cash may not cover the required withdrawals, particularly during a vacancy or major repair.
Trustees must consider diversification and insurance, but this does not automatically mean every fund must hold a broad mix of investments or purchase insurance. The decisions need to suit the fund and be documented for the auditor.
What to do now: Review your strategy alongside a cash-flow forecast, particularly if a member is approaching retirement. Record the review and your reasons, even when you decide the existing strategy remains appropriate. Discuss investment recommendations with an appropriately licensed adviser.
Frequently Asked Questions
Does an overseas trip change my Australian tax residency?
Not automatically. Travel dates are useful evidence, but residency depends on your wider circumstances, including your living arrangements and connections with Australia.
Is searching for lost super free?
Yes. You can search through ATO online services linked to myGov. Check insurance, fees and benefits before combining any accounts you find.
Does renting out my former home automatically remove its existing negative gearing treatment?
Not necessarily. The corrections protect the original acquisition date for eligible properties. Your purchase date and circumstances need to be checked, and CGT remains a separate consideration.
How often should I review my SMSF investment strategy?
The ATO expects a review at least annually. Review sooner when circumstances change, such as a member starting a pension, and document the decisions made.
Need Help With Your Tax or Super Position?
Whether you are moving overseas, finding forgotten super, changing how you use a property or reviewing your SMSF, JPR Business Group can help you understand the tax and compliance questions and plan your next steps.
Contact JPR Business GroupGeneral information for October 2026. Tax and super outcomes depend on your circumstances. Contact our team for advice relevant to your situation.